The reason behind the recent increase in your card’s interest rate
Wondering why your credit card interest rate increased? Discover the usual reasons behind these hikes, important regulations to keep in mind, and practical tips to reduce the expense of carrying a balance.
What to know about rising credit card interest rates
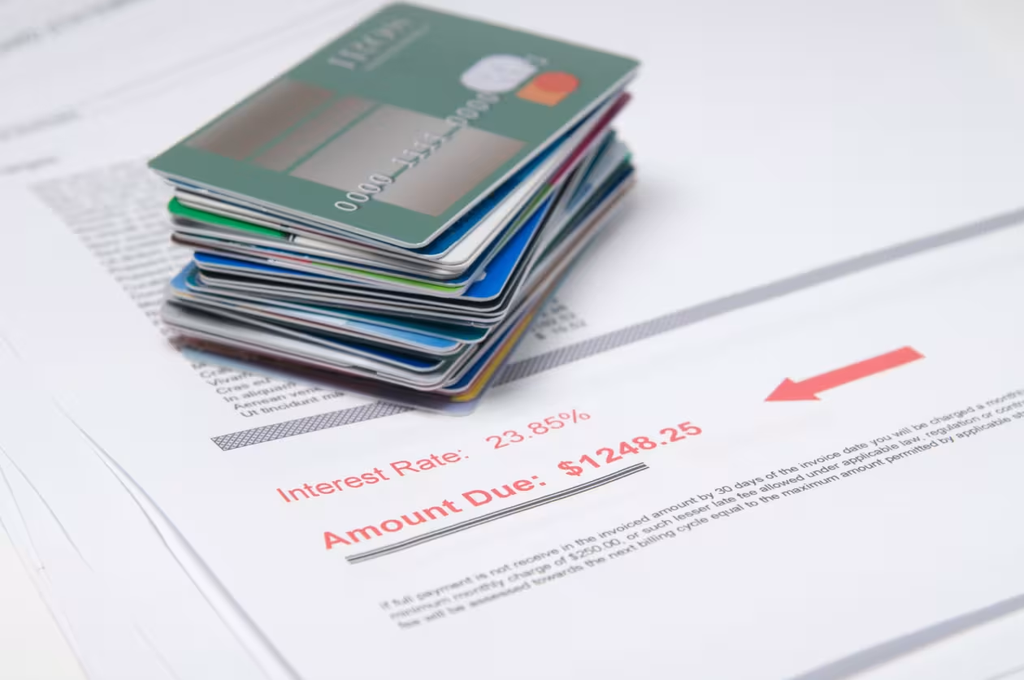
If your credit card’s interest rate suddenly appears higher, you’re not just imagining it—and it doesn’t always mean your credit score has dropped.
There are a few reasons why credit card APRs can shift. Your card might have a variable APR linked to a benchmark rate, a special introductory rate could have ended, or missing a payment might have caused your interest rate to increase under certain conditions.
When the rate on a revolving balance goes up, even a small hike can significantly increase the cost of paying down your debt.
So if you’ve looked at your statement and wondered, “Why did my APR increase?”, here’s a look at what might be behind the change—and what steps you can take.
Reasons Your Credit Card Interest Rate Increased
There isn’t a single cause for every cardholder’s APR hike. The key is to identify what kind of rate you have and what triggered the change on your account.
The most frequent reasons include:
- Your card has a variable APR tied to an index that went up;
- A promotional or introductory APR period expired;
- You missed a payment by more than 60 days;
- The issuer raised the rate on new purchases after giving proper notice;
- A special rate linked to a payment plan changed or ended.
The CFPB explains that issuers usually must give at least 45 days’ advance notice before raising interest rates on new purchases after the first year of your account, though there are exceptions and different rules depending on the type of rate adjustment.
Your Credit Card Interest Rate Might Be Variable
A major reason your card’s APR can change is because it’s variable instead of fixed.
Typically, a variable credit card APR consists of an index plus a set margin. If the index rises, your APR may go up based on your card’s terms.
The CFPB points out that if the index linked to a variable rate—like the U.S. Prime Rate—increases, the issuer is allowed to raise the rate on your current balance.
How the Federal Reserve Influences Your Credit Card APR
Your credit card’s APR is not directly determined by the Federal Reserve.
Still, the Federal Reserve’s monetary policies can affect market interest rates and the benchmark rates that lenders often follow.
In September 2026, the Federal Open Market Committee increased the federal funds target range by 0.25 percentage point to 3.75%–4.00%, citing inflation that remains above its 2% objective.
This means cardholders with variable APRs should monitor Fed rate changes, though those moves don’t always lead to identical APR increases on credit cards.
How much and when your APR adjusts depends on your card’s terms and the index it uses for variable rates.
Your Credit Card Interest Rate May Increase Following a Missed Payment
Missing a payment doesn’t necessarily cause your APR to jump right away.
Still, according to the CFPB, a card issuer may raise the interest rate on an existing balance if a minimum payment hasn’t been received within 60 days past the due date, following the rules that apply.
That’s why it’s crucial to review your payment record before assuming the rate hike is due to Federal Reserve actions.
What Happens After a 60-Day Delinquency?
If your rate went up because you were more than 60 days behind, there might be an option to return to the previous rate.
The CFPB explains that an increase triggered by a payment overdue by more than 60 days may be reversible.
Because of this, it’s worth reviewing your account’s payment history before accepting a higher APR as permanent.
Your Promotional APR Might Have Ended
Another frequent reason is less alarming: your promotional APR period finished.
For instance, a credit card may offer a low or 0% introductory APR for a limited time. After that period ends, the regular APR outlined in your card agreement will take effect.
The CFPB points out that when a temporary rate, like a balance-transfer promotional APR, expires, it can cause the interest rate on your existing balance to change.
Can a Credit Card Issuer Raise Your Interest Rate Without Prior Notice?
In most cases, issuers are required to give advance warning for major changes, but the requirements vary depending on the type of rate increase involved.
The CFPB explains that credit card issuers typically must send at least 45 days’ notice before raising the interest rate on new purchases after the account’s first year.
There are notable exceptions, such as adjustments linked to variable rates and some other specific situations.
When it comes to existing balances, the rules are stricter. Typically, issuers can only raise the rate on a current balance under certain defined conditions.
What to Watch for on Your Card Statement
If your APR changed, look through your statement or issuer messages for phrases like:
- Annual Percentage Rate (APR);
- Variable APR;
- Prime Rate;
- Effective date;
- Promotional rate expiration;
- Rate change notice.
The effective date is important because the new interest rate might not affect all existing charges on your account equally.
How Much More Could a Higher Credit Card APR Cost You?
The effect depends on your current balance and how quickly you reduce what you owe.
According to Federal Reserve data from July 2026, credit card accounts charged interest had an average APR of 22.15%.
To illustrate, here’s the interest amount on a $5,000 balance at various APR levels:
This is a simplified example assuming your balance stays the same. Actual credit card interest varies based on the issuer’s daily balance calculation and your payments.
The takeaway is clear: the higher the APR and the longer you carry a balance, the more costly your debt becomes.
This wider debt picture highlights why this is important. The New York Fed reported U.S. credit card debt hit $1.263 trillion in Q2 2026, rising $21 billion from the prior quarter.
Steps to Take If Your Credit Card Interest Rate Has Increased
Before closing your card or moving your balance, make sure to review the details carefully.
Here’s what you should do next.
1. Determine the Reason Behind the APR Increase
Either call the customer service number on your card’s back or check the notice about the rate change.
Ask questions like:
If the agent mentions the hike is linked to the Prime Rate, be sure to request the current margin and index that determine your APR.
2. Verify If Your Interest Rate Is Variable
Review the terms in your cardholder agreement.
If your APR is variable, the increase could result from an index-based change. The CFPB identifies rises in an underlying index as a valid reason for adjustments on existing balances.
3. Request a Lower APR from Your Card Issuer
There’s no harm in asking.
Try saying:
The CFPB points out that reaching out to your issuer might help reduce your interest rate. They also say issuers are usually required to regularly reassess certain rate hikes after notifying customers.
4. Stop Increasing Your Debt If Your Balance Is Rising
If you’re carrying a balance month after month, making new purchases can make it tougher to pay down your debt.
This advice is especially relevant when consumer revolving credit is still high. According to the Federal Reserve, revolving credit stood at $1.357 trillion in July 2026.
Whenever you can, try to limit card use to purchases you can pay off promptly, rather than letting a high-interest balance continue to grow.
5. Weigh Balance Transfer Offers Carefully
Transferring a balance might lower your interest costs, but don’t focus only on the introductory APR when comparing offers.
Consider these factors:
- Balance transfer fees.
- Duration of the promotional offer.
- Interest rate after the promo ends.
- If new purchases qualify for the promo rate.
- Whether you can pay off the balance before the promo expires.
A reduced rate only helps if the overall conditions actually lower your interest expenses.
Why This Is Especially Important in October 2026
For many U.S. families, October tends to be a costly month.
Expenses like Halloween treats, autumn trips, home essentials, and early holiday shopping can add up quickly on your credit card.
When these purchases roll over into future billing periods, the APR you’re paying becomes much more significant.
October also brings several key economic reports and announcements.
The Bureau of Labor Statistics will publish September’s CPI on October 14, and the Federal Reserve’s upcoming FOMC meeting is set for October 27–28.
Because of this, October is an ideal time to check your card’s terms before holiday spending ramps up.
It’s important to also consider the overall consumer landscape.
The Conference Board noted that U.S. consumer confidence dropped to 81.9 in September 2026, marking its third straight monthly decline due to worries about personal finances, inflation, and the job market.
Put simply, if your budget is already tight, carrying a balance with a high APR can make the month feel even more costly.
How Your Credit Score Relates to Your Credit Card Interest Rate
A rise in your APR doesn’t always mean your credit score has dropped suddenly.
Several factors can influence how credit cards are priced, such as:
- The card’s benchmark or index.
- The card’s fixed margin.
- Promotional-rate expiration.
- Payment history.
- The terms of your particular account.
Your credit score still plays a role when you apply for new credit; lenders often use it to decide on approval and the conditions they offer.
However, if your current card’s APR has changed, don’t jump to the conclusion that your credit score caused it before reviewing the notice and card terms.
When Should You Reach Out to Your Credit Card Issuer?
It’s a good idea to reach out to your card issuer if:
- Your APR went up and you’re unsure why.
- You never got the notice you expected.
- The rate doesn’t match your card agreement.
- Your promotional APR ended sooner than expected.
- You think a payment was wrongly marked late.
- You want to ask for a lower interest rate.
- You’re having trouble making the minimum payment.
If you think your rate was raised in error, the CFPB recommends contacting your card issuer directly.
Should the issue remain unresolved after speaking with your issuer, you can file a complaint with the Consumer Financial Protection Bureau.
Opinião do autor
It’s easy to overlook a higher APR when you’re just focused on the total shown on your monthly statement.
Yet, the interest rate is usually where the true expense of carrying a credit card balance becomes clear.
Here’s my perspective: if you see your credit card’s interest rate rise, don’t immediately blame yourself or just accept the increase without looking into it.
Begin by reviewing your statement. Note the effective date. Verify if your APR is variable. Check for any expired promotional rate or late payment triggers.
Given the current conditions, taking these extra steps is worthwhile. Credit card debt still exceeds $1.2 trillion, Federal Reserve data show average interest rates above 22% for charged accounts, and U.S. consumers continue to face high inflation and financial uncertainty.
Recommended Content
Is credit card debt wearing you down?
Discover how personal loans can lower costs, what rates look like post-Fed hike, and when it’s smart to switch.
Continue reading * You will remain on the current website