Feeling overwhelmed by credit card debt? Here’s why personal loans are becoming the preferred solution
Are you feeling the pinch of credit card debt with sky-high APRs over 22%? Discover how personal loans can help reduce your expenses, what interest rates are like following the recent Fed increase, and the best timing for making the switch.
Beware: Making only minimum payments keeps you trapped
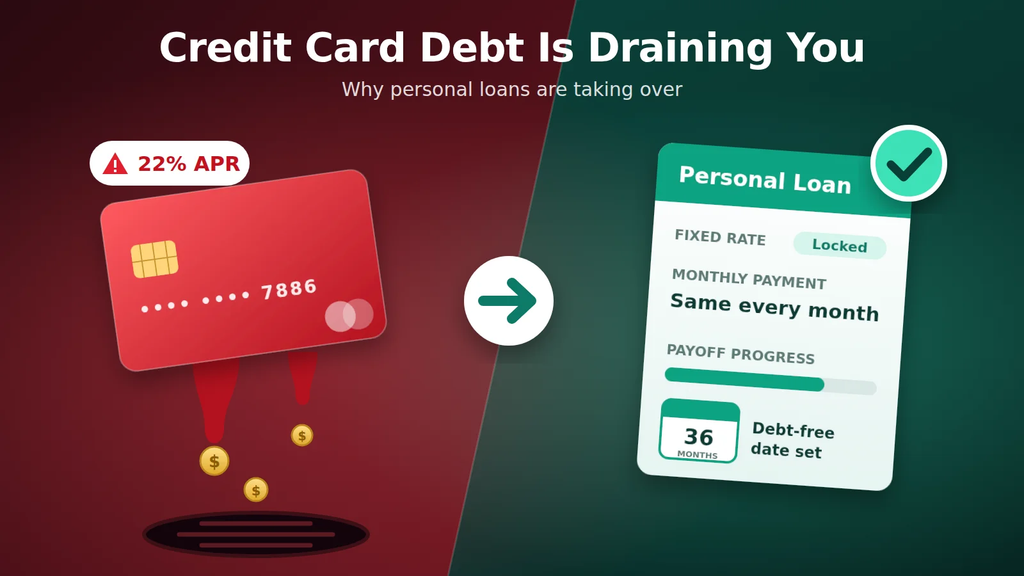
Credit card debt is draining your finances, and it’s not just a feeling.
If you glanced at your September bill and noticed back-to-school expenses added to a balance that never seems to shrink, you’re far from alone.
According to the Federal Reserve Bank of New York, Americans currently carry $1.263 trillion in credit card debt.
The outcome: millions of borrowers are quietly shifting their credit card debt into personal loans.
These loans come with fixed interest rates, consistent monthly payments, and a definite payoff date. Here’s why more people are choosing them, what the figures reveal, and how to decide if it’s right for you.
H2: Why Your Credit Card Debt Is Draining You Today
According to the latest Federal Reserve data, the average APR on credit cards that carry interest is 22.15%. Your credit score influences rates, too. WalletHub reports new card offers average 27.01% for fair credit and 23.27% for good credit.
With an average APR of 22.15%, carrying a balance of $7,886 means you’re paying roughly $146 per month in interest alone. That’s money that never reduces your principal.
The Fed’s September rate hike makes things tougher
The FOMC unanimously voted 12–0 to increase the federal funds rate to a range of 3.75%–4.00%.
Fed Chair Kevin Warsh stated that “inflation remains too high and has persisted for too long.” Currently, inflation stands at 3.4%, with 16 of 18 officials forecasting at least one more rate hike before the year ends.
Since most credit cards have a variable APR linked to the prime rate, you’ll feel the impact directly.
Ted Rossman, former lead analyst at Bankrate, notes that Fed rate adjustments “usually reach customers within one or two months” and influence both new charges and existing balances.
Back-to-school expenses have just arrived
Charges from August are now appearing on September credit card statements. According to a NerdWallet poll, 19% of parents anticipated going into credit card debt due to back-to-school expenses, while 24% planned to use Buy Now, Pay Later options.
Increasing Numbers Are Falling Behind
The New York Fed reveals that 6.97% of credit card balances entered serious delinquency (90+ days overdue) during the second quarter of 2026.
Joelle Scally, Economic Policy Advisor at the New York Fed, cautioned that “new delinquencies on auto loans and credit cards continue to stay at high levels.”
How Much Could You Save by Switching?
Can consolidating improve your credit score?
Yes, it often does. According to a TransUnion report, 68% of people who consolidated their debt boosted their credit scores by over 20 points.
Average credit card balances fell from $14,015 down to $5,855. “Debt consolidation loans typically achieve their intended purpose,” stated Liz Pagel, former SVP at TransUnion.
H2: Could a Personal Loan Be the Right Choice for You?
When a personal loan makes sense
- Your new loan’s APR is noticeably lower than your credit card’s APR, fees included;
- You can comfortably handle the fixed monthly payment;
- You’re determined to avoid racking up new card debt after paying off the balances;
- Your credit score is at least 690, qualifying you for better loan rates.
Beware of these potential pitfalls
- Origination fees: some lenders deduct these upfront, so focus on the APR, not just the interest rate;
- Fair or poor credit: average rates between 23.73% and 27.27% might not save you money;
- Increasing delinquencies: personal loan late payments (60+ days) rose to 3.81%. Borrow responsibly;
- Don’t rely on a rate cap: the suggested 10% interest limit for credit cards isn’t law yet. Waiting could mean paying more interest over time.
How to Move from Credit Card Debt to a Personal Loan in 5 Simple Steps
Step 1: Record Every Card’s Balance and APR
Before reaching out to any lender, make sure you know exactly how much you owe and what the costs are. Gather your latest statements for each card and note down:
Find the “Interest Charge” section on each statement. This is the amount you pay monthly that doesn’t reduce your principal balance at all.
The typical balance is $7,886, with an average APR of 22.15%. That adds up to roughly $146 in interest each month.
Step 2: Check Your Credit Score for Free
Your credit score is the top factor in determining the rate you’ll qualify for. The gap between different score levels can be significant:
Source: NerdWallet, September 2026.
Most banks and credit card companies let you check your credit score at no cost.
To get your complete credit reports, visit AnnualCreditReport.com, the authorized website offering free weekly reports from Equifax, Experian, and TransUnion.
Step 3: Get Prequalified by at Least Three Lenders
Prequalifying lets you see your estimated interest rate, loan amount, and monthly payment without affecting your credit score, since lenders perform only a soft credit check.
A hard credit inquiry only occurs when you submit an official loan application.
Make sure to compare at least one lender from each of these groups:
- Online lenders: fast decisions, often with funding in days, and easy online prequalification;
- Banks: may offer lower rates if you’re already a customer. The Fed reports 11.86% as the average on 24-month bank personal loans;
- Credit unions: federal credit unions are generally limited to an 18% APR ceiling. That makes them a strong option if your credit isn’t perfect.
Pro tip: choose lenders that provide “direct pay to creditor” options. This way, funds go straight to your credit card companies without passing through your bank account.
Step 4: Evaluate APR, Fees, and Overall Cost
The advertised rate rarely tells the whole story. Be sure to compare offers based on these factors:
- APR, not just the interest rate: APR includes origination fees, so it shows the true yearly cost;
- Origination fee: some lenders take it out of your loan up front. Example: with a 5% fee, you’d have to borrow about $8,301 to actually receive $7,886 to pay off your cards;
- Loan term: a longer term lowers your payment but raises your total cost;
- Prepayment penalty: make sure you can pay the loan off early without extra charges.
Here’s an example of how different term lengths affect the cost of $7,886 at a 19.55% APR:
H3: Step 5: Immediately Pay Off Your Cards and Activate Autopay
Once your loan is approved and funded, take action the very same day:
- Pay every card balance in full. If your lender offered direct pay, confirm the payments went through;
- Check each card account a few days later to confirm a $0 balance. Interest charged in the last cycle can leave a small leftover amount;
- Set up autopay on the new loan so you never miss a payment. Some lenders also give a small rate discount for autopay;
- Keep your card accounts open. Closing them can hurt your score by increasing your credit utilization and shortening your credit history.
Paying off your cards immediately lowers your credit utilization, one of the quickest ways to boost your credit score.
A TransUnion report revealed that 68% of people who consolidated their debts experienced a credit score increase exceeding 20 points.
Step 6: Keep Your Progress Secure to Avoid Falling Back Into Debt
Many people stumble here. Paying off credit cards with a loan only helps if you keep those card balances at zero.
If not, you risk ending up with twice the amount of debt.
- Take your cards out of your wallet and remove saved cards from online stores and apps;
- Plan ahead for the holidays. Holiday shopping is weeks away, so set a cash budget now, before the season starts;
- Build a small emergency fund, even $500 to $1,000. Most people rack up card debt again because of an unexpected expense, like a car repair or a medical bill;
- Turn on spending alerts in your card apps so any new charge shows up right away;
- Use your cards for one small bill only, such as a streaming service on autopay. That keeps the account active without letting a balance build up.
Author’s Opinion
Having reported on personal finance for over ten years, I can confidently say this moment stands apart.
Card balances are at all-time highs, interest rates exceed 22%, and the Fed has raised rates instead of lowering them.
Those carrying balances are feeling pressure from every direction. I’ve seen many wait for relief in rate cuts or policy caps, while their monthly interest fees quietly drain hundreds from their wallets.
A personal loan isn’t a cure-all and won’t suit everyone. If your credit score is below average, the numbers might not add up, and consulting a credit counselor could be a better first step.
However, if you can secure a significantly lower fixed rate, locking it in before another rate hike is one of the smartest moves you can make this season.
Recommended Content
Your flood insurance may expire soon
Find out what happens after your coverage ends, how the NFIP renewal period operates, and what to review beforehand.
Continue reading * You will remain on the current website