Credit Card Market: Exploring the Dual Tier Structure
Discover how the credit card landscape is dividing based on credit quality, and explore what APRs, rewards, credit scores, and debt signify for consumers in the U.S.
What’s driving the credit card market’s split into two segments?
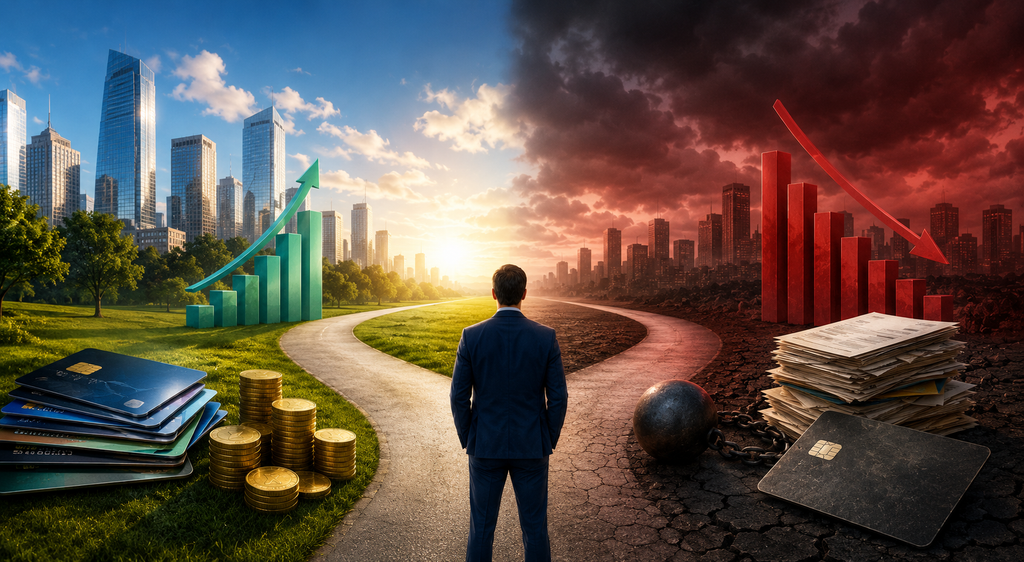
The credit card industry is increasingly segmented based on creditworthiness.
Those with strong credit profiles often qualify for cheaper offers, higher credit limits, 0% introductory APR deals, and premium reward cards.
While there’s no official “two-tier” system in the U.S. credit card market, this phrase highlights the widening gap in how consumers with different credit standings access credit card products.
Meanwhile, Bankrate noted that by late August 2026, the average credit card interest rate stood at 19.56%.
Understanding the Two-Tier Structure of the Credit Card Market
The term “two-tier credit card market” refers to the distinction between consumers with solid credit standings and those considered higher-risk borrowers.
Simply put:
The Consumer Financial Protection Bureau (CFPB) classifies credit risk into groups such as super-prime, prime, near-prime, subprime, and deep-subprime borrowers.
The framework classifies consumers with FICO Score 8 ratings of 720 and above as super-prime, while those under 580 fall into the deep subprime category.
The Importance of Credit Scores in the Credit Card Industry
Your credit score gives lenders an indication of how likely you are to repay your debts.
A higher credit score can qualify you for credit card offers with better terms and lower rates.
Conversely, a lower credit score often results in higher borrowing costs, as lenders see more risk in the account.
Put simply, your credit quality affects not just whether you get approved for a card, but also how costly that credit might be.
What’s Driving the Growing Segmentation in the Credit Card Market?
The credit card market is increasingly divided because issuers price and manage credit based on the borrower’s risk profile.
There are three key factors involved:
- Credit risk;
- Interest rates;
- Consumer demand for rewards and credit.
How Credit Risk Influences Borrowing Costs
Credit cards represent unsecured loans, meaning issuers don’t have assets like homes or cars to claim if a borrower fails to repay.
As a result, a borrower’s credit history is key in setting the conditions lenders offer for credit cards.
The CFPB has noted that credit card APR spreads have increased over the last ten years, even though the proportion of cardholders with subprime scores has stayed mostly steady.
This helps clarify why two individuals applying for credit cards simultaneously may receive very different offers.
Higher Interest Rates Increase the Cost of the Divide
Maintaining a balance on your credit card remains an expensive proposition.
According to Bankrate, the average credit card interest rate stood at 19.56% in late August 2026. While this is lower than the record high of 20.79% seen in August 2024, it’s still steep enough to make carrying debt costly.
If you pay your full statement balance every month, the APR usually doesn’t affect you much.
However, for those who carry a balance, the APR often becomes one of the most critical figures on their statement.
How the Two Market Tiers Influence Credit Card Rewards
The split impacts more than just interest rates.
It also influences access to rewards, special promotions, and exclusive card perks.
Consumers with Strong Credit Usually Have More Reward Choices
Those with higher credit scores often qualify for cards that provide:
- Cash back
- Travel rewards
- Welcome bonuses
- 0% introductory APR offers
- Airport lounge access
- Travel credits
- Purchase protections
For instance, NerdWallet’s current credit card listings have separate sections for 0% APR cards and rewards cards, highlighting the strong competition among these types of credit products.
However, rewards shouldn’t automatically be seen as a form of savings.
A card offering 2% cash back can earn you $20 back on $1,000 in qualifying purchases.
Yet if that spending adds to a balance that builds interest, the debt cost can quickly surpass the value of the rewards earned.
Consumers with Lower Credit Scores Often Receive Fewer Rewards Benefits
The CFPB has identified notable disparities in rewards offered across different credit-risk categories.
According to its 2023 consumer credit card report, subprime cardholders earned less than one percentage point in annual rewards value relative to their balances, whereas super-prime users with higher spending could lower their effective credit costs by nearly five percentage points through rewards.
This highlights a key feature of the two-tier credit card market:
Those who tend to gain the most from rewards programs are usually the ones able to pay off their balances in full and avoid interest charges.
How the Two-Tier Credit Card Market Impacts You
The actual effects will mostly depend on whether you carry a balance and the strength of your credit profile.
If Your Credit Is Strong
With a solid credit history and a habit of paying your balance in full, you likely have more options to choose from, such as:
- Lower-cost credit
- 0% introductory APR offers
- Cash-back cards
- Travel rewards
- Premium benefits
- Higher credit limits
Qualifying for a premium card doesn’t always mean it’s the best option for you.
Be sure to weigh the annual fee, interest rate, and the true worth of any rewards offered.
If Your Credit Is Fair or Poor
When your credit score is lower, your approach to choosing a card might need to change.
Rather than focusing mainly on rewards, consider these factors instead:
- APR
- Annual fees
- Security deposit requirements
- Credit limit
- Reporting to the major credit bureaus
- Late-payment policies
- Opportunities to build a positive payment history
According to CFPB data, consumers with below-prime credit often face much higher APR margins, making borrowing costs especially critical.
A credit card that supports rebuilding your score affordably can be more beneficial than one offering flashy rewards.
How to Maximize Your Benefits in the Credit Card Market
You don’t have to have perfect credit to make smarter choices with credit cards.
Your aim should be to select a card that fits your financial needs.
Review Your Credit Before Applying
Begin by checking your credit score and credit report details.
The CFPB’s credit risk model helps lenders identify different tiers of creditworthiness.
Understanding your credit standing can prevent you from applying for cards that don’t suit you.
Prioritize APR Over Rewards When Comparing Cards
If you tend to carry a balance, your primary focus should often be the card’s APR.
For instance, a card offering a slightly lower cashback rate but a much lower APR might be a better fit for those who usually carry debt.
According to Bankrate’s latest figures, the average credit card interest rate hovers around 20%, highlighting how costly revolving balances can become.
Avoid Letting Rewards Drive You to Overspend
Rewards exist primarily to motivate cardholders to use their cards more often.
That doesn’t mean rewards are bad. However, you should never let them justify spending beyond what you can repay.
Here’s a straightforward tip: if you can’t comfortably pay off your balance, prioritize calculating the interest charges before focusing on rewards.
Key Credit Card Market Trends to Watch in 2026
Looking ahead, the credit card market will likely stay closely linked to consumer credit quality, interest rates, and overall household debt levels.
Lenders Are Focusing More on Credit Risk
According to TransUnion, U.S. consumer credit is increasingly following a K-shaped pattern, with lenders treating credit risk very differently across various tiers.
For instance, new credit card limits for super-prime borrowers grew by 11.5% to $12,511, while new limits for deep-subprime borrowers increased 5.5% to $678.
That difference is quite substantial.
This indicates that credit access isn’t simply growing or shrinking uniformly across the market.
Access to credit is growing much quicker for certain consumers compared to others.
Interest Rates Will Remain a Key Factor
Credit card interest rates are strongly influenced by the overall interest rate environment.
Since many credit cards feature variable APRs, shifts in benchmark rates can ultimately impact borrowing expenses.
For those who carry a balance, even minor APR changes can significantly affect costs over time.
Rewards Will Stay Competitive, but They Aren’t Free Money
Issuers continue to use rewards as a key strategy to attract and keep customers.
However, the true benefit of rewards hinges on how cardholders manage and use their credit cards.
The CFPB has studied how rewards, card usage, and credit costs interact, revealing notable differences among various credit-risk categories.
Therefore, consumers should view rewards as just one part of the overall financial picture of a card, rather than as a benefit on its own.
The Author’s Perspective
One of the biggest errors consumers make when navigating the credit card world is assuming that everyone faces the same conditions.
That’s not the case. Someone with excellent credit who pays their balance in full each month often views credit cards as a tool to earn cash back, rack up travel points, or benefit from promotional offers.
On the other hand, a person carrying a balance with a high interest rate will experience this same market in a very different way.
That’s why I think the best way to grasp the “two-tier” credit card market isn’t just to look at which cards exist.
Instead, ask yourself: What is the real cost of my credit?
If your credit profile qualifies you for better deals, make sure to use that benefit wisely.
When your credit is less strong, prioritize strengthening your financial health rather than pursuing rewards that might not offer real value.
Recommended Content
Student loan collection
Learn who is at risk, what collections can take and how to protect your finances.
Continue reading * You will remain on the current website