Why the annual fee on your card keeps rising
Wondering why your credit card’s annual fee keeps going up? Discover the factors behind these hikes and find out how to determine if your card still offers good value.
Is your credit card costing more? Keep an eye on the annual fee
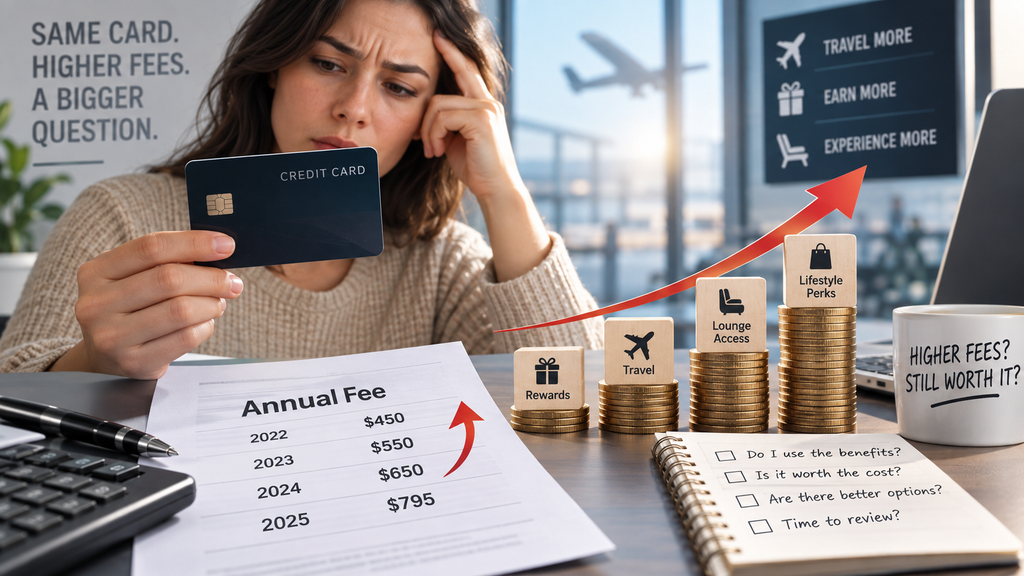
Your credit card annual fee might keep climbing as issuers raise prices on premium rewards, add travel and lifestyle perks, tweak card economics, and target higher-spending customers with repositioned products.
Paying a higher fee doesn’t necessarily mean the card is either a better or worse value.
The main consideration is whether the perks you actually use justify the increased annual fee.
Why Is My Credit Card Annual Fee Increasing?
Credit card annual fees may rise when the issuer updates the card’s pricing structure or changes its benefits.
Premium credit cards have been adding more travel credits, lounge access, rewards, and lifestyle perks, often alongside higher annual fees.
For instance, some recent updates to premium cards have pushed their annual fees to around or above $800 each year.
A key difference is between the value the issuer promotes and the actual benefit you gain personally.
What Causes Credit Card Annual Fees to Go Up?
Common reasons for these increases include:
- Added travel credits
- Expanded airport lounge perks
- Increased rewards rates
- New hotel or dining perks
- Extra statement credits
- Updates to the card’s rewards program
- Rising costs of premium rewards features
- Shifting focus toward higher-spending cardholders
Are Annual Fees Climbing Across Credit Cards?
Fee hikes have been especially noticeable among premium credit cards.
The Federal Reserve Bank of New York reported that U.S. credit card debt reached $1.26 trillion in Q2 2026, highlighting credit cards’ ongoing role in managing household budgets.
At the high-end segment, some cards now come with annual fees reaching several hundred dollars, with a few products nearing or surpassing $800 per year.
What’s Driving Premium Credit Cards to Raise Their Annual Fees?
Premium cards are increasingly competing by bundling together travel perks and lifestyle benefits.
Thus, a higher annual fee often corresponds to a pricier set of benefits, but more perks don’t always translate to greater value for every user.
How Travel Credits Can Reduce the Impact of a High Annual Fee
Imagine a card with a $795 annual fee that offers $300 in travel credits.
The straightforward math looks like this: $795 − $300 = $495
However, that $300 only holds its full value if you would have spent that amount on qualifying purchases regardless.
If you redeem just $150 of the credit, the real value to you is closer to $150, not the full $300.
Understanding this difference is crucial when assessing premium credit cards.
The Value of Airport Lounge Access Varies Among Different Travelers
Access to airport lounges can offer great benefits for those who travel often.
For travelers who fly multiple times annually, lounge access might replace expenses they’d otherwise incur at airports.
But for those who seldom travel by air, this perk often holds little real benefit.
Don’t judge a benefit by its listed price tag. Instead, focus on the actual savings it provides you.
Rewards Are Only Worthwhile When They Align With Your Spending Habits
A higher rewards rate can help balance out an annual fee if it applies to purchases you already plan to make.
However, spending extra just to earn rewards often undermines their benefit.
For instance, if a card gives bonus points on dining, charging an unnecessary $500 dinner doesn’t actually save you money.
Rewards should complement your spending patterns, not drive them.
Should You Keep Your Credit Card After the Annual Fee Goes Up?
Before deciding whether to hold onto, switch, or cancel your card, weigh several important considerations.
Look at How It Compares to Cards Without Annual Fees
Don’t limit your comparison to just other high-end cards.
Evaluate its net yearly worth against a card with no annual fee at all.
Check With Your Issuer About Switching Products
Before deciding to close your account, find out if your issuer offers the option to switch to a different card.
Depending on your issuer and the type of account, you might be able to transfer to a card with a lower or no annual fee.
Options differ depending on the issuer.
Is It Legal for Credit Card Companies to Increase Your Annual Fee?
Federal regulations generally allow credit card issuers to raise certain annual or monthly fees after the first year, as long as specific rules are met.
Regulation Z along with CFPB guidelines set the requirements for notifying consumers about some credit card term changes.
Certain updates mandate 45 days’ advance notice, though the exact notice period varies depending on the specific change involved.
What Is the Required Notice Period from Credit Card Issuers?
When changes fall under Regulation Z, consumers are typically provided with advance notification ahead of the update.
The notice should outline key details such as:
- The updated fee amount
- The date the change begins
- Which account terms are impacted
- Any rights or choices you have
Always review the issuer’s notice carefully, as rules may vary by fee type and account details.
Is It Possible to Avoid Paying a Credit Card Annual Fee?
Sometimes you can. Here are some options to consider:
- Switching to a no-fee card from the same credit issuer;
- Checking if you can switch to a different card product;
- Evaluating the card compared to other options you have;
- Contacting the issuer to ask about retention offers;
- Closing the card only after weighing possible credit impacts.
Does Closing a Credit Card Impact Your Credit Score?
Shutting down a credit card can influence factors that affect your credit score.
A key aspect to keep in mind is credit utilization.
What Actions Should You Take If You Carry a Credit Card Balance?
If you carry a balance month to month, don’t let the annual fee be your only worry.
The Federal Reserve Bank of New York noted that U.S. credit card debt reached $1.26 trillion in Q2 2026.
For cardholders with revolving debt, interest charges often outweigh the financial benefits of maximizing rewards.
Should You Spend More to Offset an Annual Fee?
Never base financial decisions on extra spending you wouldn’t normally do just to cover an annual fee.
When a card has a $500 annual fee, spending thousands more just to rack up rewards can actually raise your costs instead of lowering them.
The aim isn’t to earn enough rewards to make extra spending worthwhile.
Instead, it’s about getting the most value from purchases you were already planning to make.
Author’s Perspective
An increase in your credit card annual fee calls for a fresh evaluation, particularly when the hike reaches several hundred dollars.
What really matters isn’t if the issuer has added more perks, but whether those perks fit how you actually spend, travel, and use your card.
When you already take advantage of the credits and rewards, the higher fee might be worth it because it covers benefits you’d use anyway.
But if you don’t redeem those perks, the stated value can be deceiving for your personal finances.
The easiest way to judge is by asking: how much did I actually save over the past year, and how much did I spend on the card’s fee?
That calculation offers a clearer view than relying on the marketing values assigned to every benefit.
If you carry a balance, keep in mind that managing rewards effectively should come after fully grasping your interest expenses.
Recommended Content
Health insurance
Health insurance options may change. Learn why premiums could rise, insurers may exit markets and how to prepare.
Continue reading * You will remain on the current website